Introduction & Background
Financial planning is no longer a one-size-fits-all process. Whether you are just starting your career, raising a family, or preparing for retirement, your financial needs and goals evolve with each life stage. Traditional approaches to money management often fail to address these shifting priorities, leaving many people feeling overwhelmed or unprepared. The concept of “smart money moves” introduces a dynamic, adaptable framework that aligns financial strategies with real-life circumstances. By taking a fresh approach to financial planning, individuals can build resilience, reduce stress, and create opportunities for long-term success. This article explores how to tailor financial decisions to fit every phase of life, ensuring that money works as a tool for growth rather than a source of worry.
Concept & Overview
Smart money moves represent a proactive and flexible method of managing finances that prioritizes long-term stability while remaining responsive to immediate needs. Unlike rigid financial models, this approach encourages continuous learning and adjustment. At its core, smart money management involves understanding your unique financial landscape, setting realistic goals, and making informed decisions that align with both short-term priorities and long-term aspirations. It is not about following a fixed set of rules but about developing a mindset that values adaptability, discipline, and foresight. By integrating principles of budgeting, saving, investing, and risk management, individuals can create a personalized roadmap for financial success at every stage of life.
Key Features & Highlights
- Personalized Strategies: Financial plans are tailored to individual circumstances, considering factors such as income, expenses, family size, career goals, and risk tolerance.
- Goal-Oriented Planning: Clear, measurable goals are established, whether saving for a home, funding education, or building a retirement nest egg.
- Flexible Budgeting: Budgets are designed to be adjustable, allowing for changes in income or unexpected expenses without derailing financial progress.
- Emergency Preparedness: A dedicated emergency fund is prioritized to cover unforeseen events, reducing reliance on debt or last-minute financial scrambles.
- Debt Management: Strategies for paying down high-interest debt efficiently are incorporated to free up future income for savings and investments.
- Investment Diversification: A mix of assets is maintained to balance risk and return, ensuring growth while protecting against market volatility.
- Continuous Learning: Staying informed about financial trends, tax laws, and market opportunities helps refine strategies over time.
Frequently Asked Questions / Pros & Cons
What are the main advantages of adopting a smart money approach?
One of the primary benefits is the ability to align financial decisions with personal values and life goals. This approach fosters financial security by encouraging consistent saving and mindful spending. It also reduces financial anxiety by providing a clear roadmap, allowing individuals to focus on what matters most in their lives. Additionally, smart money moves often lead to better credit scores, lower debt burdens, and improved access to financial opportunities like loans or investments.
Are there any drawbacks to this method?
While the benefits are substantial, smart money management requires discipline and ongoing effort. It may involve making sacrifices in the short term, such as delaying gratification for long-term rewards. Some people find the process overwhelming initially, especially if they lack financial literacy or support. Additionally, unexpected life events can disrupt even the best-laid plans, necessitating regular reviews and adjustments.
How does smart money management differ from traditional financial planning?
Traditional financial planning often follows a linear path, with fixed milestones such as saving for retirement in your 20s or paying off a mortgage by 40. In contrast, smart money management embraces flexibility and personalization. It acknowledges that life does not follow a predictable script and that financial strategies must adapt to changing priorities, such as career shifts, family expansions, or health challenges.
Is this approach suitable for people with low or irregular incomes?
Absolutely. Smart money moves are designed to be inclusive and adaptable. Even with limited income, small, consistent steps like setting aside even a few dollars weekly can build a foundation. Irregular income earners can benefit from creating flexible budgets that account for fluctuating cash flow, prioritizing essential expenses, and building a buffer for lean periods.
Practical Guidance & Solutions
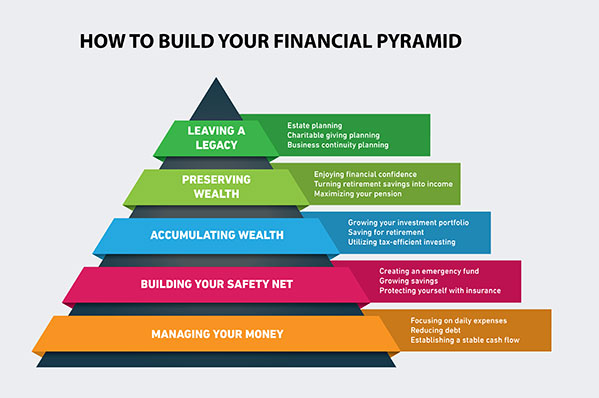
To implement smart money moves effectively, start by assessing your current financial situation. Calculate your net worth, track your spending for a month, and identify areas where you can cut back or optimize. Next, define your short, medium, and long-term goals. For example, if you are saving for a down payment, determine how much you need and set a realistic timeline.
Create a flexible budget that separates needs from wants, and allocate funds accordingly. Automate savings and bill payments to remove the temptation to overspend. If debt is a burden, focus on paying off high-interest obligations first while making minimum payments on others. Consider consolidating debt or negotiating lower interest rates to accelerate repayment.
Investing does not have to be complicated. Start with low-cost index funds or retirement accounts like a 401(k) or IRA. If you are risk-averse, prioritize guaranteed growth options such as certificates of deposit or high-yield savings accounts. For those willing to take on more risk, diversify across asset classes like stocks, bonds, and real estate to spread risk.
Finally, review and adjust your plan regularly. Life changes, and so should your financial strategy. Whether it is a new job, a growing family, or an unexpected expense, staying proactive ensures your plan remains relevant and effective.
Conclusion
Smart money moves offer a refreshing alternative to rigid financial planning by focusing on adaptability, personalization, and informed decision-making. By embracing this approach, individuals at any life stage can take control of their finances, reduce stress, and build a secure future. The key is to start small, stay consistent, and remain open to learning and adjusting along the way. Whether you are saving for a dream vacation, paying off student loans, or planning for retirement, a thoughtful, proactive approach to money can turn financial goals into achievable realities. Begin today, and empower yourself to make every dollar work harder for you.